Property Taxes and HOA Dues: What You Can Really Afford
Imagine two houses listed at $400,000. Same price, same number of bedrooms, maybe even the same paint color. Your monthly payment could still be hundreds of dollars apart. Why? Because the sticker price is not the bill. Your real housing payment is principal, interest, property taxes, homeowners insurance and HOA dues combined. Most buyers focus on the first two, and that is exactly how people end up stretching too far for a home a lender said they could afford. The Census Bureau's latest release confirms that the cost of homeownership continues to rise.
This post will help you avoid that trap. We will start with why two identically priced homes cost different amounts, then walk through the mortgage affordability formula known as PITI plus HOA. You will see a worked example with two $400,000 homes and two very different monthly bills. We will also separate lender limits from your personal comfort zone, dig into property taxes and insurance, and look at how HOA dues can grow with little notice. Finally, you will learn how to use an online mortgage affordability calculator the right way, plus next steps before you start shopping.
Why Two Identically Priced Homes Cost Different Amounts
A listing price tells you loan size, not monthly bill. Two homes listed at $400,000 can sit $300 to $700 apart per month once local property taxes, insurance premiums and HOA dues are added.
That gap is widening. The Census Bureau's 2025 ACS 1-year release, headlined "The Cost of Homeownership Continues to Rise," shows carrying costs climbing nationwide, though exact figures should be confirmed against the full release before quoting. A 2025 analysis of Census data found condo or HOA fees topped $500 a month for about 3 million households. Dues that size rival a car payment for many buyers.
Budget from principal and interest alone and you can get pre-approved for a payment you cannot comfortably sustain. Once escrow collects taxes and insurance and HOA dues come due, monthly reality hits.
We will walk through the carrying cost formula, a side-by-side comparison of two same-priced homes, the gap between lender limits and personal comfort, and how to run an online mortgage affordability calculator the right way, including the costs most calculators leave out.
The Mortgage Affordability Formula: PITI Plus HOA
PITI stands for principal, interest, taxes and insurance. Add HOA dues and you get your true monthly housing payment, also called the full carrying cost. The mortgage affordability formula to repeat: monthly principal + monthly interest + monthly property tax + monthly homeowners insurance + monthly HOA dues, plus mortgage insurance if your down payment is under 20 percent. The CFPB defines PITI as those four core parts.
Most of these bills arrive annually. Divide the yearly property tax bill by 12. Divide the annual insurance premium by 12. Divide quarterly HOA dues by 3, or annual dues by 12. The math works the same on paper or in an online mortgage affordability calculator. The real question is whether the tool asks for taxes, insurance and HOA dues at all. Our home affordability tools at can-i-afford-it.org show each carrying cost on its own line. You can see exactly which one stretches your budget instead of staring at one unexplained total. For more on what calculators measure and miss, read our FAQ guide.
Two $400,000 Homes, Two Very Different Monthly Bills
Both homes list at $400,000. Both buyers put 20 percent down ($80,000) and take a 30-year fixed loan at an illustrative 7.4 percent, near where rates averaged 7.40 percent in early October 2026. Each loan is $320,000. Every figure below is an estimate, not a quote.
Home A sits in a lower tax district with no HOA. Principal and interest: about $2,216. Taxes: roughly $330 a month. Insurance: about $125.
Home B sits in a higher tax district and charges $450 in HOA dues. Principal and interest stay at $2,216. Taxes: about $600. Insurance: about $150.
Cost | Home A | Home B |
|---|---|---|
Principal and interest | $2,216 | $2,216 |
Property tax | $330 | $600 |
Insurance | $125 | $150 |
HOA dues | $0 | $450 |
Total monthly | $2,671 | $3,416 |
Monthly gap | $745 | |
Annual gap | $8,940 |
That $745 monthly gap is worth roughly $107,000 in borrowing power at 7.4 percent. Home B costs the same on paper but swallows a whole price tier of budget.
Tax rates, insurance premiums and dues vary widely by location. Pull your county's rate and get a real quote, then run both sides of the comparison yourself before shopping.
Lender Limits vs. Your Comfort Zone: Two Different Numbers
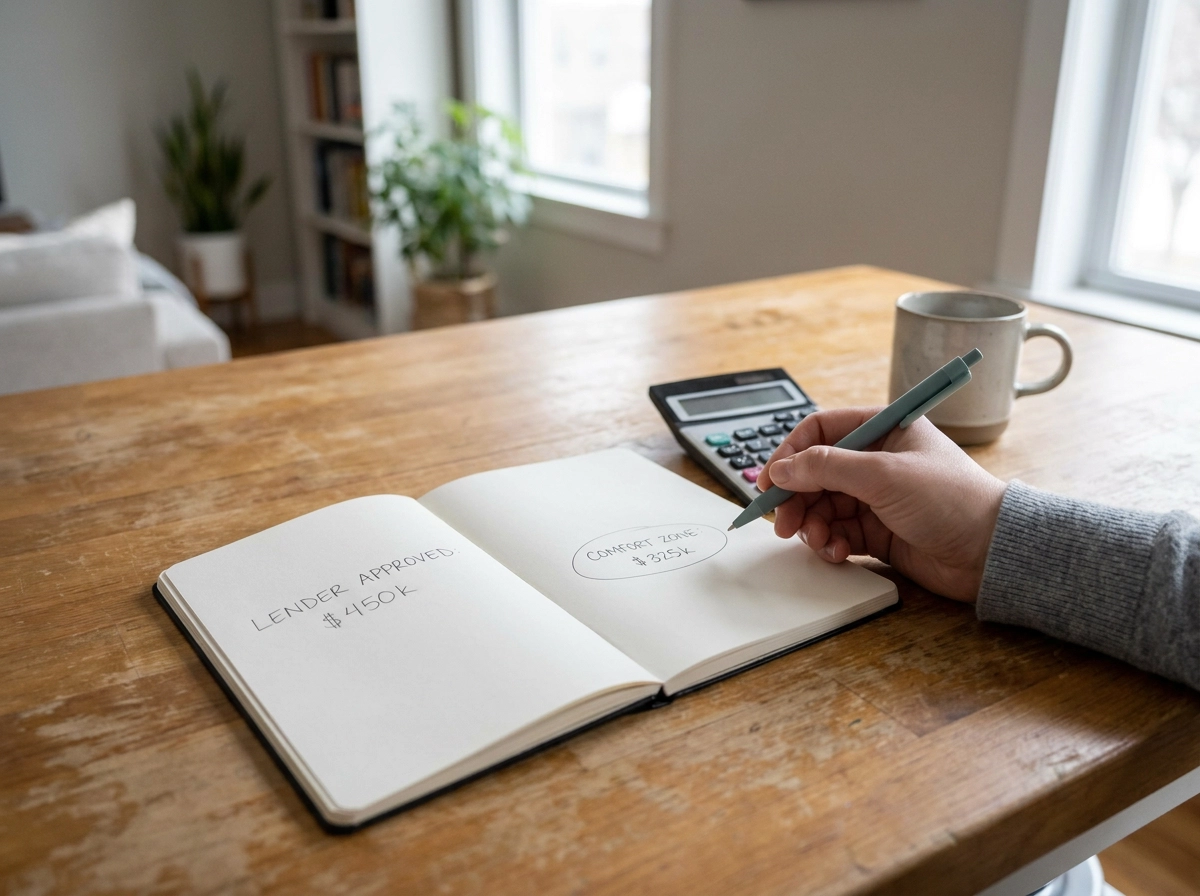
Those two $400,000 homes showed how carrying costs change the monthly bill. Now compare that bill to two very different numbers: what a lender will approve and what you can comfortably pay.
Your debt-to-income ratio, or DTI is the share of your gross monthly income that goes to all debt payments. Lenders often want total debts under roughly 36% to 43%, and some guidelines allow 45% or higher. Fannie Mae's underwriting guidelines set these caps for loan eligibility.
Here is the key point: DTI is a ceiling, not advice. Qualifying for a payment and enjoying it are separate things. Many buyers aim to keep housing between 25% and 30% of take-home pay. That leaves room for savings, retirement, childcare, and surprise repairs.
Adding taxes, insurance, and HOA dues raises your DTI and shrinks your monthly cushion. Try this today: subtract the full PITI plus HOA figure from your take-home pay. Then ask whether what remains covers the rest of your life without leaning on credit cards.
Property Taxes: The Variable You Can Research Before You Shop
Here is the good news: unlike insurance or HOA dues, property taxes are public and researchable before you make an offer. Rates are set locally, so they can swing sharply between neighboring towns, counties, and even school districts a few miles apart.
Find the real number in three places: the county assessor or treasurer website, the tax history shown on the listing, or the seller's most recent tax bill, which your agent can request. Just treat the current owner's bill as a starting point, not a promise. A recent sale, new construction, or a completed reassessment can reset the assessed value after you buy. Some states cap how much assessed value or the tax bill can rise each year; others do not. Ask your county how reassessment works before you make an offer. And keep this in mind: a more expensive home in a low tax area can cost less per month than a cheaper home in a high tax area. Price alone is a poor affordability filter. Local rates matter, just like checking your own rent zone matters when you rent.
Homeowners Insurance: A Small Line Item With a Big Swing
Unlike property taxes, insurance is required by your lender. Most buyers pay it monthly into escrow along with taxes, so it belongs in your PITI plus HOA formula, not a separate mental bucket.
What drives the premium? Location, roof age and material, construction type, claims history, coverage limits, your deductible, and local risk for wind, hail, wildfire, or flooding. In higher risk areas, premiums can run several times the national average. Flood coverage is almost always a separate policy.
Before you get attached to an address, check FEMA flood maps. Flood insurance can add a meaningful monthly cost in some zones. Leave room for everything else in your budget by pricing this early.
To lower the premium: bundle auto and home coverage, raise your deductible to an amount you could actually pay, and improve the roof or add storm mitigation features.
HOA Dues: The Payment That Can Grow Without Much Notice
Insurance is only one piece of the monthly puzzle. If a home belongs to a homeowners association (HOA), you will also pay HOA dues. These are recurring fees, usually monthly or quarterly, that fund shared areas, exterior maintenance, amenities, and reserve accounts for future repairs.
What those dues cover varies a lot. Some associations pay for water, trash, roofing, and siding. Others only handle landscaping and common lighting. So the same dollar amount can mean very different things from one community to the next.
Two risks buyers miss most: annual dues increases and special assessments. A special assessment is a one-time charge when the reserve fund is short for a big repair. Before you make an offer, review the last two years of HOA budgets, reserve studies, and board meeting minutes. Look for large upcoming projects, lawsuits, or repeated special assessments. Census data shows about 3 million households pay more than $500 a month in condo or HOA fees. Dues that high are not a rounding error. Add that number to your PITI total before you trust any affordability estimate.
Using an Online Mortgage Affordability Calculator the Right Way
Once you know the dues, check what the calculator asks for. Many quick tools default to principal and interest only. If yours never asks about taxes, insurance and HOA dues, its answer is a floor, not your actual payment. Then enter the purchase price, down payment, interest rate and loan term. Add the annual property tax, annual insurance premium and monthly HOA dues. Only then trust the total. Run the same numbers two or three times with different towns, tax rates or HOA levels. You will watch each carrying cost cut into your price range. For the full monthly picture, Connecting Your Finished Budget to an Affordability Calculator can help. can-i-afford-it.org's home affordability calculator separates each cost, so you can spot whether taxes, insurance or dues are doing the damage and adjust from there. Remember: any result is an estimate. Confirm it with a lender's Loan Estimate and a real insurance quote for that address before you commit.
FAQ: Carrying Costs and What You Can Afford
Once you have run a few calculator estimates, these questions tend to come up.
Is PITI the same as my mortgage payment? PITI stands for principal, interest, taxes and insurance. If you have an escrow account, your monthly payment to the lender usually bundles the tax and insurance portions, so the amount you send often is PITI.
How much do HOA dues add to a mortgage? Many associations charge a few hundred dollars a month. Census data shows about 3 million households pay more than $500 monthly. Check the specific community's documents for the real number.
Does the mortgage affordability formula include utilities, lawn care or internet? No. PITI plus HOA covers property-tied costs. Utilities, internet and lawn care are separate and deserve their own budget line.
Will property taxes change after I buy? They can. A new sale, new construction or a scheduled reassessment may reset assessed value. Ask your county how and when values update.
My calculator says I can afford more than my pre-approval. What should I do? Use the lower number as your starting point. Neither figure accounts for savings goals, which matter most. For a related sanity check, see the 28/36 rule, briefly.
Your Next Steps Before You Start Shopping
Now that you know what PITI and HOA dues actually cover, put the math to work before you tour a single house.
Start by writing down your true monthly housing payment: principal, interest, property tax, insurance and HOA dues. If your down payment is under 20 percent, add mortgage insurance too. This is the number that hits your bank account, not just the loan payment.
Next, look up the actual tax rate for every town on your list. Request two or three real insurance quotes for a specific address before you fall in love with a house. Rates and premiums vary too much to guess.
For any home with dues, read the HOA budget, reserve study and recent meeting minutes. Ask directly about planned special assessments.
Finally, run the numbers on our affordability tools so you see each carrying cost as its own line. Compare that total against both your lender's DTI limit and your own comfort level. Shop from the lower of the two.
Conclusion
The sticker price is only the beginning. Two homes listed at the same amount can carry very different monthly costs once property taxes, insurance, mortgage insurance, and HOA dues enter the picture. Your lender's DTI limit tells you what you can borrow, not what you should comfortably spend. Research tax rates town by town, request real insurance quotes for specific addresses, and read the HOA budget before you commit. Then run the totals on our affordability tools so you see every carrying cost as its own line. Shop from the lower of your lender's limit and your own comfort zone. Do this homework first, and you will tour homes with confidence, make stronger offers, and choose a payment that feels right every month.
Frequently asked questions
- What is PITI, and how is it different from my total monthly housing cost?
- PITI stands for principal, interest, property taxes and homeowners insurance. Your full monthly housing cost, also called carrying cost, adds HOA dues and mortgage insurance if your down payment is under 20 percent. If you have an escrow account, the amount you send your lender often bundles taxes and insurance, so it may look close to PITI, but HOA dues are typically paid separately.
- Why do two homes at the same price have different monthly payments?
- The listing price only sets the loan size. Monthly costs also depend on local property tax rates, homeowners insurance premiums and HOA dues, which can vary widely between neighborhoods. In the post's example, two $400,000 homes differed by $745 per month because of taxes, insurance and HOA dues.
- How do I convert annual property taxes, insurance and HOA dues into monthly amounts?
- Divide the yearly property tax bill by 12 and the annual insurance premium by 12. For HOA dues, divide quarterly dues by 3 or annual dues by 12. Add these monthly figures to principal and interest to estimate your true monthly housing payment.
- What is the difference between a lender's DTI limit and my comfort zone?
- Debt-to-income ratio (DTI) is the share of gross monthly income going to debt payments, and lenders often allow totals up to roughly 36% to 45%, depending on the loan. That is a ceiling for approval, not advice. Many buyers aim to keep housing costs between 25% and 30% of take-home pay so they have room for savings, retirement, childcare and emergencies.
- What should I check about HOA dues before making an offer?
- Review the last two years of HOA budgets, the reserve study and board meeting minutes. Look for large upcoming projects, lawsuits, planned special assessments and annual dues increases. Also confirm what the dues cover, since some associations include water, trash, roofing and siding while others cover only landscaping and common lighting.
Run your own numbers
Rent Affordability Calculator
LiveFind a rent that fits your income comfortably.
Car Affordability Calculator
LiveSee what car payment your budget can handle.
Emergency Fund Calculator
LiveWork out how big your safety net should be.
Debt Payoff Calculator
LivePlan a realistic path to becoming debt-free.
Monthly Survival Number Calculator
LiveKnow the minimum you need each month.
Move Out Calculator
LiveCheck if you're ready to live on your own.
Home Affordability Calculator
LiveSee how much house you can really afford.
Cost of Living Calculator
LiveSee if a rising cost of living still fits your budget.
How Much of My Income Should Go to Rent?
LiveCheck your rent against the 30/40/50% guideline thresholds.
Mortgage Payoff Calculator
LiveSee how much sooner extra payments clear your mortgage.